Standard Black-Karasinski model class. More...
#include <blackkarasinski.hpp>
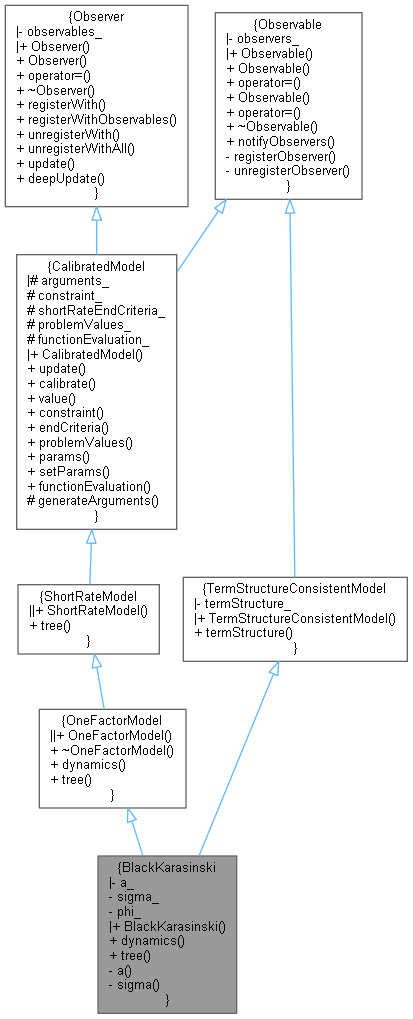
 Inheritance diagram for BlackKarasinski:
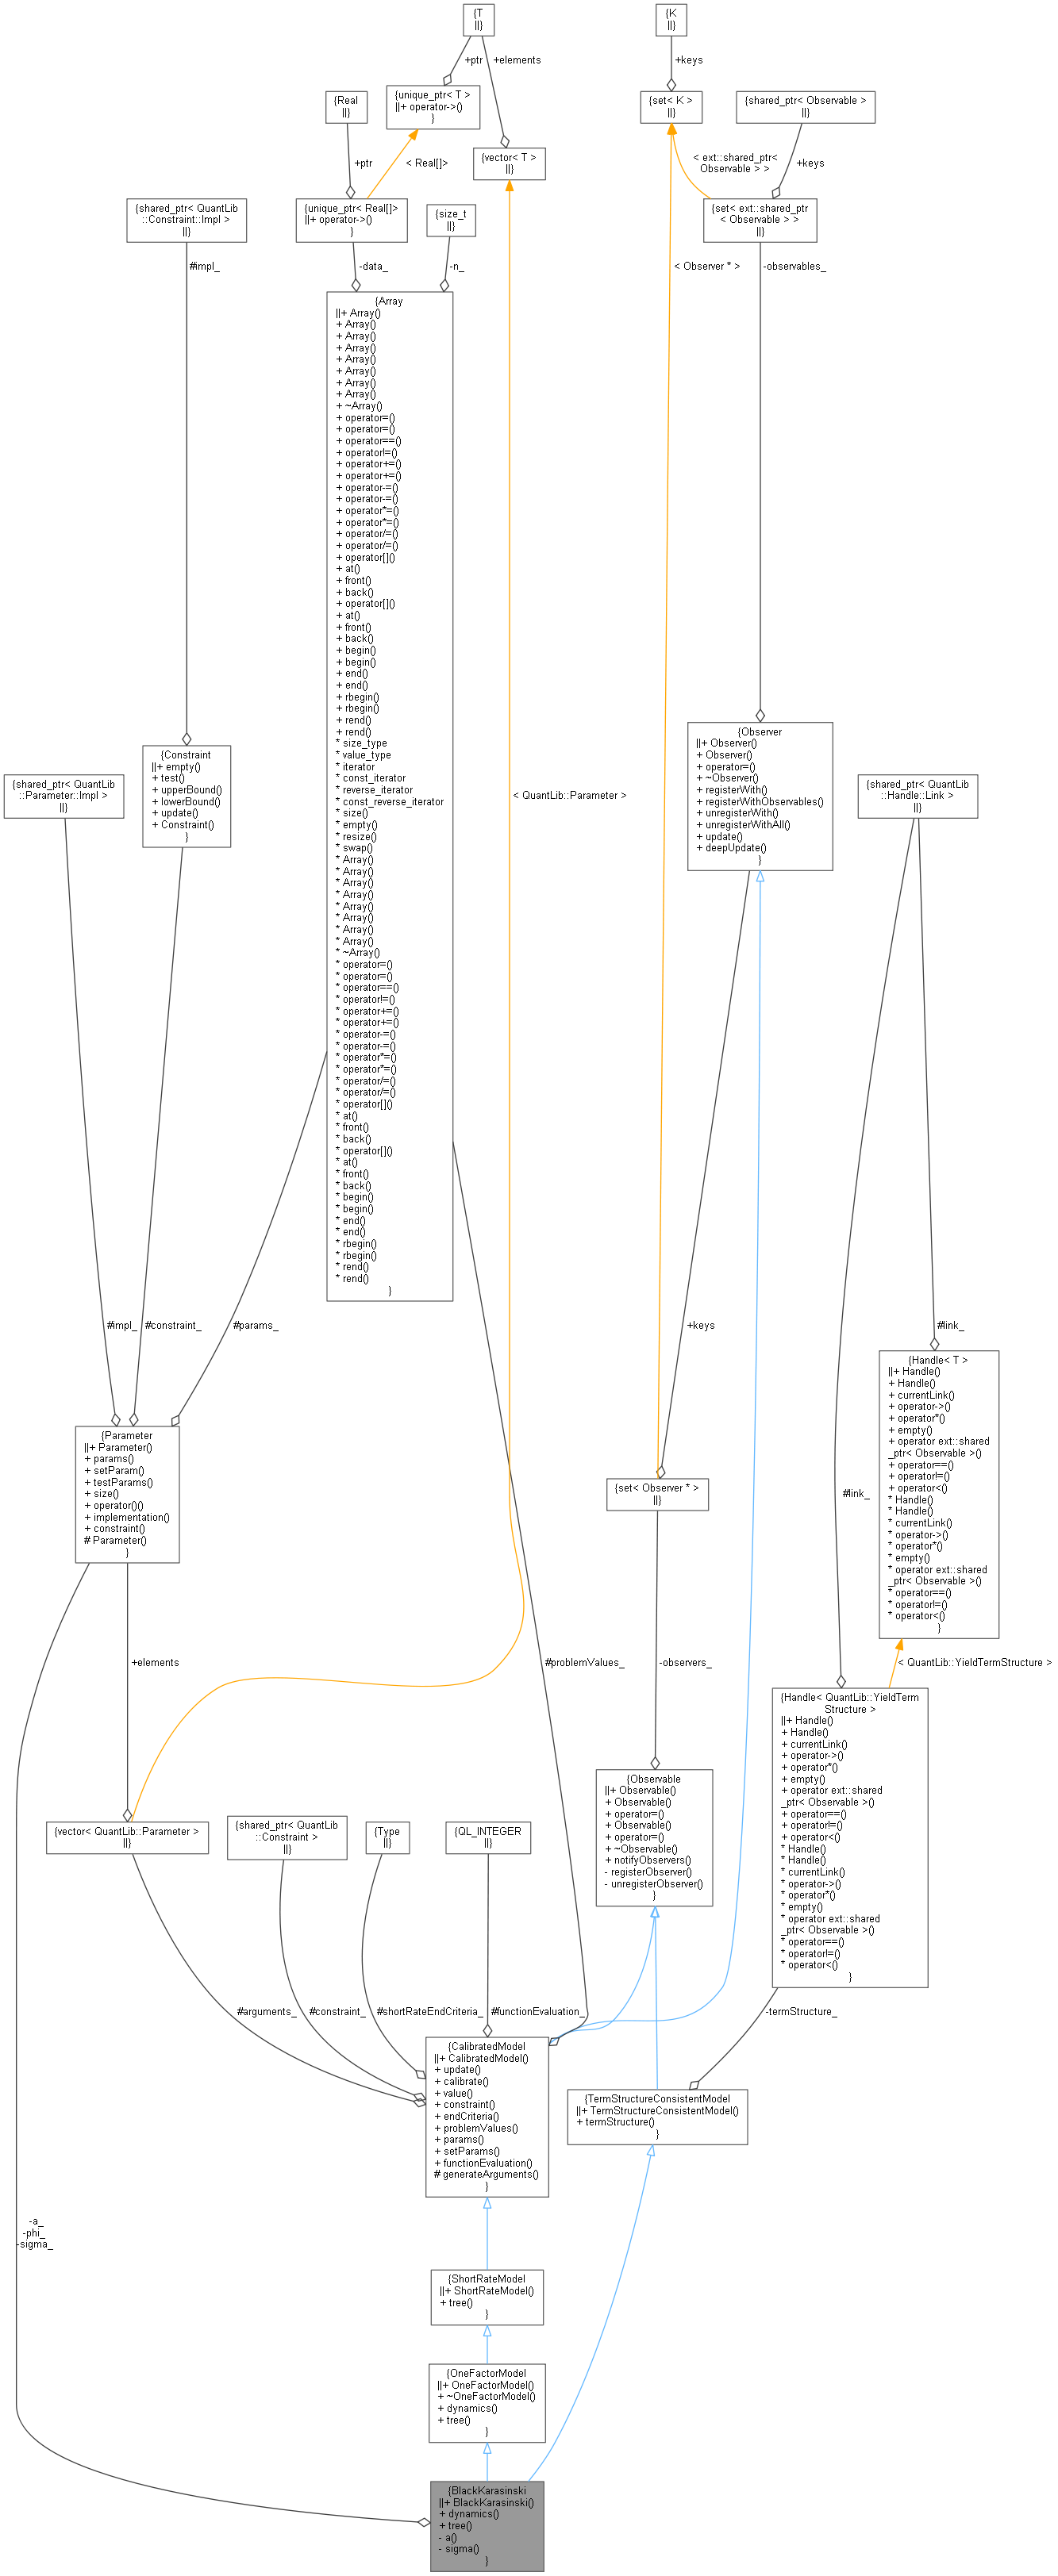
 Collaboration diagram for BlackKarasinski:
Classes | |
| class | Dynamics |
| Short-rate dynamics in the Black-Karasinski model. More... | |
Public Member Functions | |
| BlackKarasinski (const Handle< YieldTermStructure > &termStructure, Real a=0.1, Real sigma=0.1) | |
| ext::shared_ptr< ShortRateDynamics > | dynamics () const override |
| returns the short-rate dynamics More... | |
| ext::shared_ptr< Lattice > | tree (const TimeGrid &grid) const override |
| Return by default a trinomial recombining tree. More... | |
| Public Member Functions inherited from OneFactorModel | |
| OneFactorModel (Size nArguments) | |
| ~OneFactorModel () override=default | |
| virtual ext::shared_ptr< ShortRateDynamics > | dynamics () const =0 |
| returns the short-rate dynamics More... | |
| ext::shared_ptr< Lattice > | tree (const TimeGrid &grid) const override |
| Return by default a trinomial recombining tree. More... | |
| Public Member Functions inherited from ShortRateModel | |
| ShortRateModel (Size nArguments) | |
| virtual ext::shared_ptr< Lattice > | tree (const TimeGrid &) const =0 |
| Public Member Functions inherited from CalibratedModel | |
| CalibratedModel (Size nArguments) | |
| void | update () override |
| virtual void | calibrate (const std::vector< ext::shared_ptr< CalibrationHelper > > &, OptimizationMethod &method, const EndCriteria &endCriteria, const Constraint &constraint=Constraint(), const std::vector< Real > &weights=std::vector< Real >(), const std::vector< bool > &fixParameters=std::vector< bool >()) |
| Calibrate to a set of market instruments (usually caps/swaptions) More... | |
| Real | value (const Array ¶ms, const std::vector< ext::shared_ptr< CalibrationHelper > > &) |
| const ext::shared_ptr< Constraint > & | constraint () const |
| EndCriteria::Type | endCriteria () const |
| Returns end criteria result. More... | |
| const Array & | problemValues () const |
| Returns the problem values. More... | |
| Array | params () const |
| Returns array of arguments on which calibration is done. More... | |
| virtual void | setParams (const Array ¶ms) |
| Integer | functionEvaluation () const |
| Public Member Functions inherited from Observer | |
| Observer ()=default | |
| Observer (const Observer &) | |
| Observer & | operator= (const Observer &) |
| virtual | ~Observer () |
| std::pair< iterator, bool > | registerWith (const ext::shared_ptr< Observable > &) |
| void | registerWithObservables (const ext::shared_ptr< Observer > &) |
| Size | unregisterWith (const ext::shared_ptr< Observable > &) |
| void | unregisterWithAll () |
| virtual void | update ()=0 |
| virtual void | deepUpdate () |
| Public Member Functions inherited from Observable | |
| Observable ()=default | |
| Observable (const Observable &) | |
| Observable & | operator= (const Observable &) |
| Observable (Observable &&)=delete | |
| Observable & | operator= (Observable &&)=delete |
| virtual | ~Observable ()=default |
| void | notifyObservers () |
| Public Member Functions inherited from TermStructureConsistentModel | |
| TermStructureConsistentModel (Handle< YieldTermStructure > termStructure) | |
| const Handle< YieldTermStructure > & | termStructure () const |
Private Member Functions | |
| Real | a () const |
| Real | sigma () const |
Private Attributes | |
| Parameter & | a_ |
| Parameter & | sigma_ |
| Parameter | phi_ |
Additional Inherited Members | |
| Public Types inherited from Observer | |
| typedef set_type::iterator | iterator |
| Protected Member Functions inherited from CalibratedModel | |
| virtual void | generateArguments () |
| Protected Attributes inherited from CalibratedModel | |
| std::vector< Parameter > | arguments_ |
| ext::shared_ptr< Constraint > | constraint_ |
| EndCriteria::Type | shortRateEndCriteria_ = EndCriteria::None |
| Array | problemValues_ |
| Integer | functionEvaluation_ |
Detailed Description
Standard Black-Karasinski model class.
This class implements the standard Black-Karasinski model defined by
\[ d\ln r_t = (\theta(t) - \alpha \ln r_t)dt + \sigma dW_t, \]
where \( alpha \) and \( sigma \) are constants.
Definition at line 42 of file blackkarasinski.hpp.
Constructor & Destructor Documentation
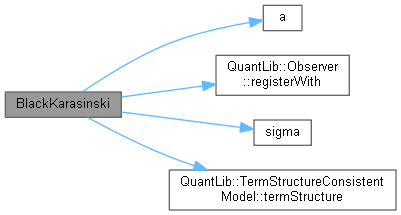
◆ BlackKarasinski()
| BlackKarasinski | ( | const Handle< YieldTermStructure > & | termStructure, |
| Real | a = 0.1, |
||
| Real | sigma = 0.1 |
||
| ) |
Member Function Documentation
◆ dynamics()
|
overridevirtual |
returns the short-rate dynamics
Implements OneFactorModel.
Definition at line 100 of file blackkarasinski.cpp.
Here is the call graph for this function: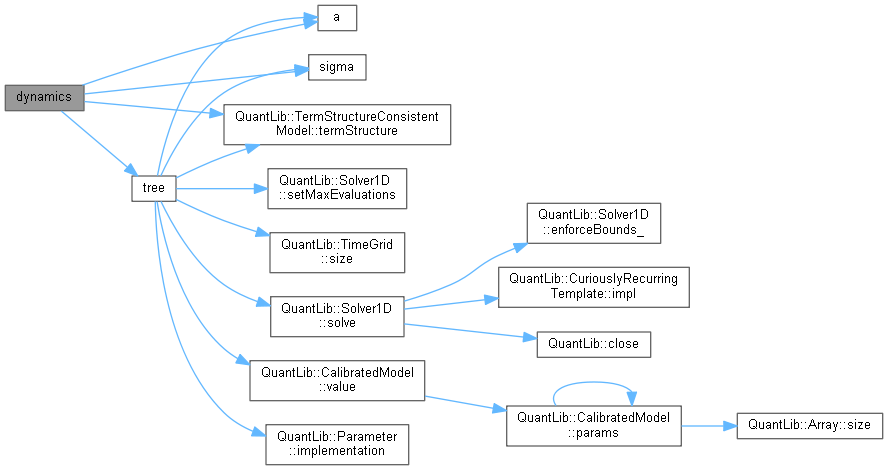
◆ tree()
Return by default a trinomial recombining tree.
Reimplemented from OneFactorModel.
Definition at line 70 of file blackkarasinski.cpp.
Here is the call graph for this function: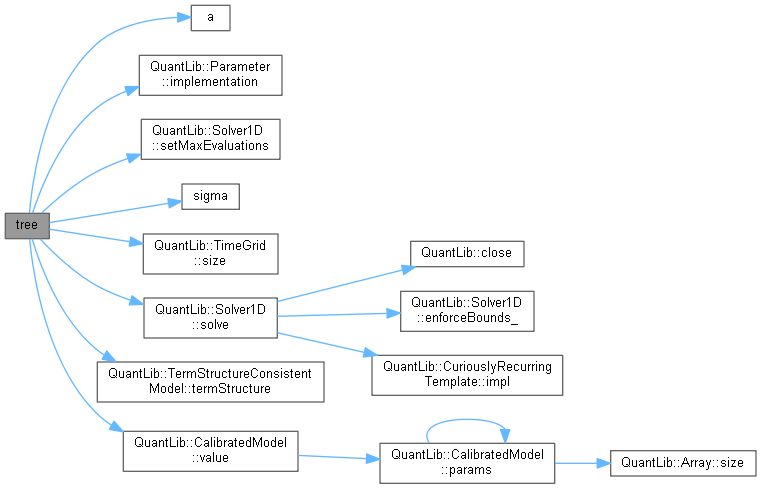 Here is the caller graph for this function:
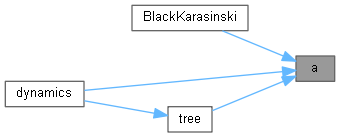
◆ a()
|
private |
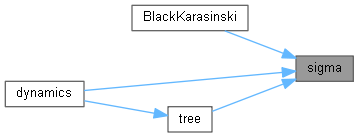
◆ sigma()
|
private |
Member Data Documentation
◆ a_
|
private |
Definition at line 59 of file blackkarasinski.hpp.
◆ sigma_
|
private |
Definition at line 60 of file blackkarasinski.hpp.
◆ phi_
|
private |
Definition at line 61 of file blackkarasinski.hpp.